
Fixed Deposit or Corporate Bond?
What is holding retail investors back?
India’s corporate bond market has grown from ₹17.5 lakh crore at the end of FY15 to over ₹60 lakh crore. Bonds can now be bought for as little as ₹10,000, and online bond platforms are SEBI-regulated. Yet retail investors hold about ₹1.2 lakh crore in corporate bonds, against ₹152 lakh crore in fixed deposits. It may be time to revisit how your debt allocation is split, using three lenses: returns, risk and liquidity.
1. Returns: bonds pay more, even at AAA
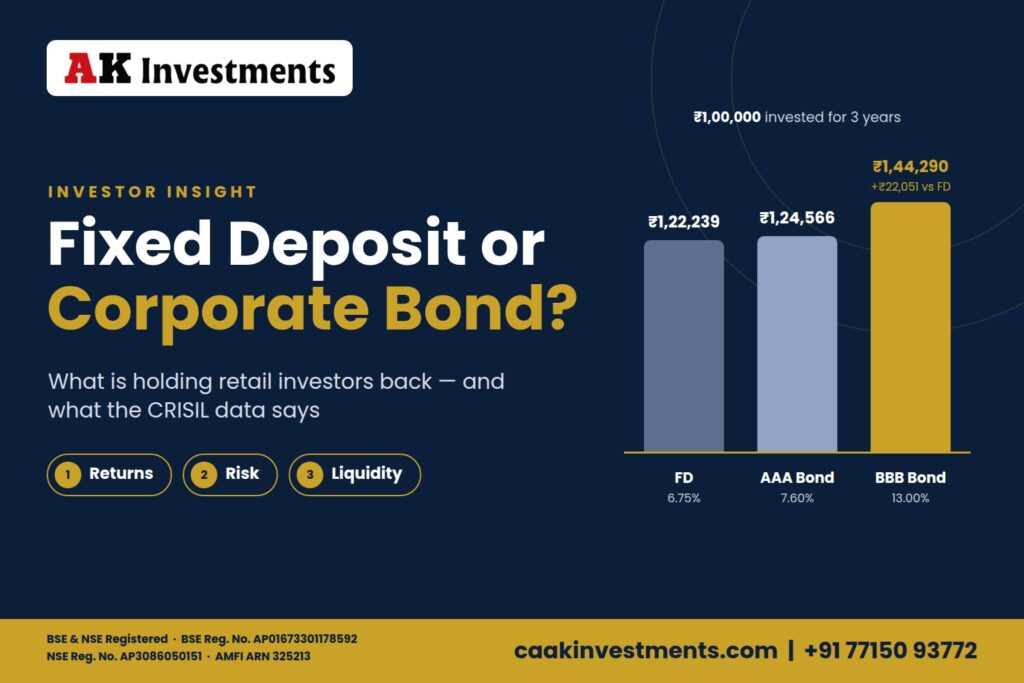
Over three years, a AAA bond earns more than an FD, and a BBB bond earns considerably more. The higher return is compensation for higher risk, which is where the next question comes in.
₹1,00,000 invested for 3 years
Option | Yield | Value after 3 years | Difference vs FD |
Fixed deposit | 6.75% | ₹1,22,239 | – |
AAA-rated bond | 7.60% | ₹1,24,566 | +₹2,327 |
BBB-rated bond | 13.00% | ₹1,44,290 | +₹22,051 |
Illustrative, pre-tax. FD compounded quarterly; bonds compounded annually.
2. Risk: default and downgrade, by the numbers
The chance of non-payment is real but small for investment-grade issuers. As per CRISIL, no AAA-rated entity defaulted within three years. For BBB-rated entities, the three-year default rate was 1.97%, and 0.43% over one year.
CRISIL’s cumulative default rate (%), FY16–26
Rating | One-year | Two-year | Three-year |
CRISIL AAA | 0.00 | 0.00 | 0.00 |
CRISIL AA | 0.02 | 0.07 | 0.14 |
CRISIL A | 0.07 | 0.33 | 0.58 |
CRISIL BBB | 0.43 | 1.15 | 1.97 |
A downgrade affects the bond’s market price, which matters only if you sell before maturity. Held to maturity, interest continues and principal is repaid on the due date. CRISIL data shows 99% of AAA ratings stay unchanged over a year, and fewer than 5% of BBB ratings move lower.
Average one-year rating movement (%), FY16–26 (downgraded includes default)
Rating | Upgraded | Unchanged | Downgraded |
CRISIL AAA | – | 99.03 | 0.98 |
CRISIL AA | 2.28 | 96.05 | 1.67 |
CRISIL A | 4.17 | 92.81 | 3.01 |
CRISIL BBB | 3.76 | 91.64 | 4.60 |
3. Liquidity: easy to buy, harder to sell
An FD can be broken on any working day, usually at a reduced rate. Bond liquidity varies: higher-rated bonds trade more readily, while lower-rated bonds can be hard to sell. The 29 online bond platforms now operating have made buying as simple as opening a deposit. As more retail investors participate, the secondary market should deepen.
The takeawayAn FD’s real advantage is certainty of exit, not a higher return. Money you may need at short notice belongs in deposits. For long-term goals, investment-grade bonds held to maturity are now a practical alternative, and AK Investments can help you select them. |
Adapted from “From Director’s Desk” by Sashi Krishnan, Director, NISM (nism.ac.in). Data: CRISIL Default and Rating Transition Study 2026.
Disclaimer: For investor education only; not investment advice or an offer. Figures are illustrative and pre-tax. Fixed returns are not guaranteed or assured. Investments in corporate debt securities, municipal debt securities / securitized debt instruments carry credit, market and default risks including delay and/or default in payment. Past default and transition rates do not indicate future outcomes. Read all offer related documents carefully.